YOUR HOME SOLD GUARANTEED OR WE'LL BUY IT!*
Canadian Home Sales Dip as Housing Market Remains Largely Stable
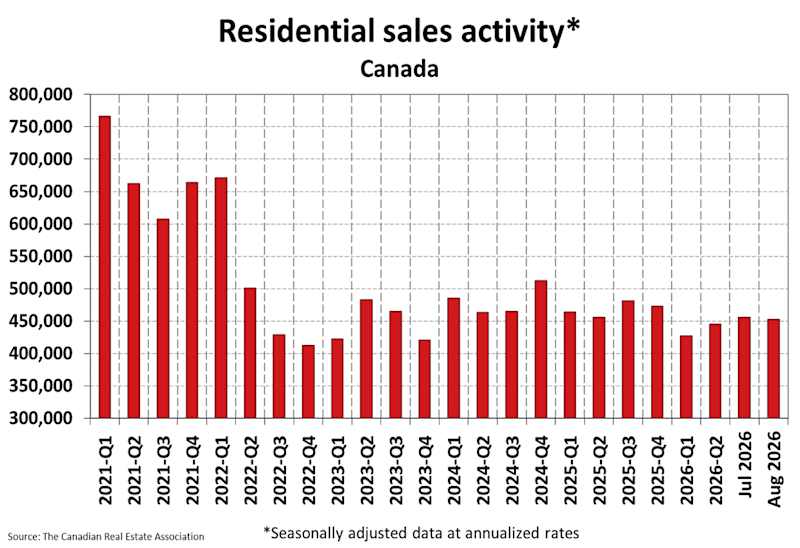
Canadian home sales decreased 0.7% month over month in August 2026, marking a fourth consecutive month of largely unchanged activity. Actual sales were 6.9% lower than in August 2025, while new listings increased 3.3% compared with July. The increase in listings reversed three consecutive monthly declines and pointed to a broader return of properties to the market as the fall season approached.
The rise in new listings, combined with the slight decline in sales, pushed the national sales-to-new-listings ratio down to 49.1% in August from 51.1% in July. The long-term average is 54.7%, with readings between roughly 45% and 65% generally considered consistent with balanced market conditions. There were just under 200,000 properties listed for sale across Canadian MLS® Systems at the end of August, broadly in line with historical levels and 1.4% higher than a year earlier.
National housing inventory remained at 4.8 months in August, unchanged for the fourth consecutive month and slightly below the long-term average of five months. Based on historical measures, inventory below 3.6 months would indicate a seller's market, while more than 6.4 months would indicate a buyer's market. Overall supply has remained relatively stable since spring 2025, suggesting that neither sales nor available inventory has shifted dramatically in recent months.
Home prices were also largely stable in August. The National Composite MLS® Home Price Index was unchanged from July, extending a period of month-to-month price stability that has lasted since the spring. Compared with August 2025, the index was down 3%, although the annual decline has been narrowing since January. August's decline was the smallest year-over-year decrease since October 2025.
The national average home price was $668,219 in August 2026, up 0.6% from a year earlier. While housing activity and prices have remained relatively steady, the broader economic environment has become less certain, with rising inflation risks and questions about the durability of economic growth creating additional headwinds. Fixed mortgage rates have already increased alongside higher bond yields, while financial markets are pricing in the possibility of a variable-rate increase later this year. These factors could limit further momentum in the housing market as the country moves toward 2027.